The Best Pay-Per-Mile Car Insurance Programs in the U.S. Right Now
The Best Pay-Per-Mile Car Insurance Programs in the U.S. Right Now
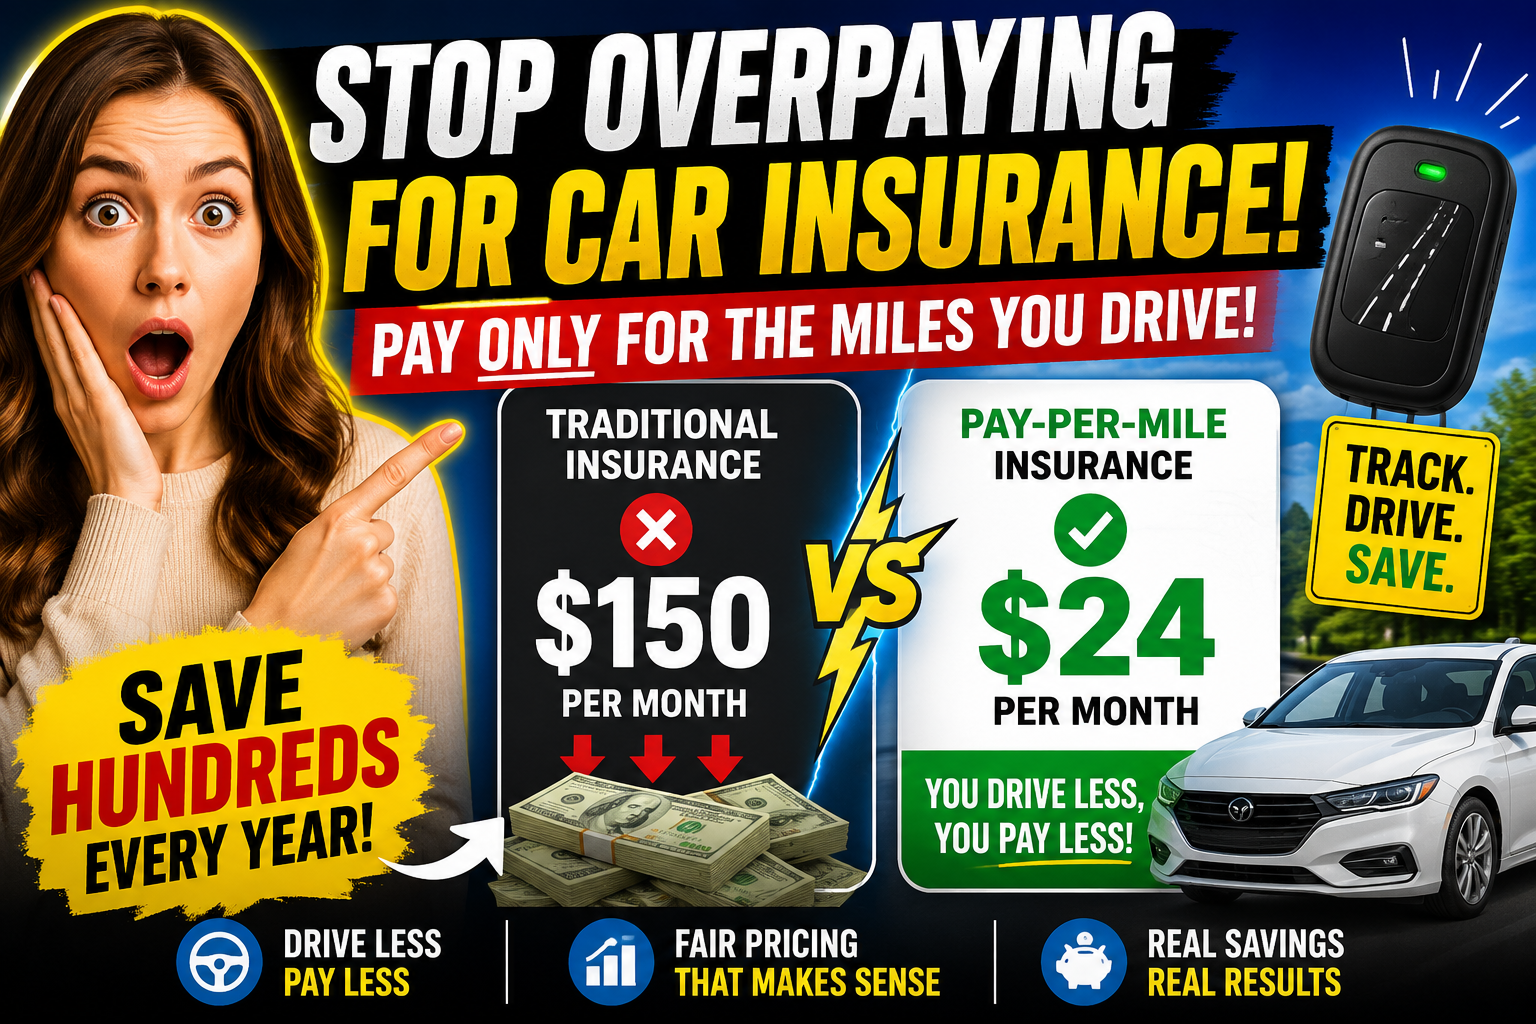
You're paying for something you barely use. And somehow, that's become completely normal.
Most American drivers hand over hundreds of dollars every month to their insurance company — rain or shine, commute or no commute. But here's the thing: the average car sits parked for about 95% of its life. So why are millions of people still paying a flat premium as if they're driving cross-country every weekend?
That's the question pay-per-mile car insurance was built to answer.
What Is Pay-Per-Mile Insurance, and Why Is Everyone Talking About It?
Pay-per-mile insurance is exactly what it sounds like. Instead of paying a flat monthly premium regardless of how much you drive, you pay a fixed base rate plus a variable per-mile fee.
The per-mile rate typically runs between two and ten cents per mile. That might sound tiny. But multiply it by how few miles you actually drive in a slow month, and the savings start to look very real.
Low-mileage drivers — those under 10,000 miles annually — typically save 30 to 40% compared to traditional policies. For someone paying $1,200 a year right now, that's $360 to $480 back in your pocket. Every single year.
This isn't a gimmick. This is insurance finally adapting to how people actually live.
Who Is This Actually For?
Stop and think about your own driving habits for a second.
Do you work from home three or four days a week? Do you live in a city where you mostly walk or take transit? Are you a retiree who only drives to appointments and the grocery store? Do you have a second car that mostly sits in the garage?
Pay-per-mile coverage is a cost-effective option for remote workers, retirees, self-employed people, and infrequent drivers. It also makes a lot of sense for college students who left their car at home, or young professionals who bike to work but keep a car for weekends.
The national average is about 13,473 miles per year. If you're driving significantly under that number, there's a real chance you're overpaying with a traditional policy right now.
The Top Pay-Per-Mile Programs Worth Your Attention
Let's get into the actual programs. Not all of them are equal, and the right one depends heavily on your state, your mileage, and how comfortable you are with tracking technology.
1. Nationwide SmartMiles — The Most Accessible Option
As of April 2026, SmartMiles is available in 44 states — every state except Alaska, Hawaii, Louisiana, North Carolina, Oklahoma, and New York. That's the broadest reach of any pay-per-mile program in the country right now.
Nationwide SmartMiles offers a 250-mile daily cap and safe driving discounts up to 10%. The daily cap is a big deal — it means even if you take a long road trip, your bill won't go through the roof for that one month.
When you sign up for SmartMiles, Nationwide monitors your driving to count your miles traveled. It also pays attention to your other driving habits — things like hard braking, fast acceleration, and late-night driving between midnight and 5 a.m. — and if the company considers you a safe driver, it will lower your premium by up to 10%.
For most people comparing pay-per-mile options for the first time, SmartMiles is the safest starting point.
2. Allstate Milewise — Best for Cars That Sit Idle
Milewise works a little differently from most programs. Allstate charges a daily base rate — for example, $1.50 — plus a per-mile rate — for example, six cents — for covered vehicles.
The daily billing structure is actually a clever feature. If your car sits in the garage for three days, you're only paying that base rate on those days — not a per-mile charge on top. Allstate Milewise is genuinely best for cars that sit unused for multiple days.
Milewise is offered in 22 states: Arizona, Delaware, Florida, Idaho, Illinois, Indiana, Maryland, Massachusetts, Michigan, Minnesota, Missouri, New Jersey, Ohio, Oklahoma, Oregon, Pennsylvania, Rhode Island, South Carolina, Texas, Virginia, Washington, and West Virginia.
One caveat worth knowing: Allstate doesn't offer discounts on Milewise, so your savings depend entirely on how little you drive. No safe-driver rewards, no bundling perks. Pure mileage math.
3. Metromile (via Lemonade) — Built for Minimal Drivers
Metromile was one of the original pay-per-mile specialists, and it was acquired by Lemonade in 2022. Important to note: Lemonade is no longer offering new Metromile quotes. If you're looking for pay-per-mile insurance, you'll want to check Lemonade's current offerings directly.
Still, the legacy numbers are instructive. According to the company, the average driver saves 47% compared to a standard insurance policy.
Metromile advertises a sample rate of $29 per month plus six cents for each mile driven. For someone driving just 300 miles a month, that works out to roughly $47 total — a fraction of what traditional insurance costs in most states.
4. USAA SafePilot Miles — Best for Military Families
If you're active duty, a veteran, or an eligible family member, this one deserves serious attention.
USAA has a reputation for its affordable insurance premiums. A standard USAA auto insurance policy costs roughly $1,533 per year on average. For a SafePilot Miles policy, you could pay around $1,282 — or even less if you get deployed.
SafePilot Miles policies already have affordable premiums, but you can save up to 20% more by making safe driving decisions. Factors tracked include mileage, smoothness of driving, and other behavioral metrics.
As of April 2026, SafePilot is available in all states except Alaska, California, Connecticut, Maryland, Michigan, New Jersey, New York, North Carolina, Pennsylvania, Vermont, and Washington.
5. Mile Auto — For the Privacy-Conscious Driver
Here's the one that's different from everything else on this list.
Mile Auto is the only pay-per-mile option with no tracking device. Privacy-conscious drivers simply submit odometer photos instead. No plug-in dongle. No smartphone app monitoring your location. Just a photo of your odometer each month.
Mile Auto focuses exclusively on pay-per-mile coverage and claims that drivers can save up to 30% or 40% on car insurance compared to traditional rates.
If the idea of a device tracking your every move makes you uncomfortable, Mile Auto is the answer.
A Real-World Example: What the Numbers Actually Look Like
Here's how the math played out for one driver profile, based on published rate data.
A retiree driving about 4,800 miles per year with a traditional premium of $165 per month could switch to Allstate Milewise — at a daily rate of $0.75 plus six cents per mile — and end up paying roughly $46.81 per month. That's an annual saving of $1,418.
That's not a typo. Over $1,400 a year — saved simply by paying for what you actually use.
The Honest Downsides You Should Know About
Pay-per-mile insurance isn't perfect for everyone. Knowing where it falls short is just as important as knowing where it shines.
Pay-per-mile insurance can disappoint when your mileage creeps up, your billing becomes less predictable than expected, or the carrier's tracking style doesn't match your comfort level.
It's also worth doing the math with your current discounts. A standard carrier may give you strong bundling, accident-free, homeowner, or multi-car discounts that erase the advantage of the by-the-mile model entirely.
And availability remains a real limitation. Metromile operates in only eight states. Even Milewise only covers 22. If you live in a state with limited options, Nationwide SmartMiles is likely your best — and sometimes only — realistic choice.
How to Know If You'd Actually Save Money
The answer comes down to one number: your annual mileage.
Pay-per-mile insurance is usually worth it only for people who drive less than 12,000 miles annually, which is the national average.
Here's a simple way to check. Pull up your last car service receipt — it has your odometer reading. Then think back to your service before that. The difference is roughly how many miles you've driven in that period. Annualize it. If that number is under 10,000, you should absolutely be getting pay-per-mile quotes.
Most pay-per-mile companies also require customers to drive a car from 1996 or later in order to be compatible with a mileage-tracking device. If your car is older than that, Mile Auto's photo-based system may be the only option that works for you.
The Bottom Line
The U.S. car insurance industry has been charging people for miles they never drive for decades. Pay-per-mile programs are finally changing that math.
Pay-per-mile insurance is ideal for low-mileage drivers with fewer than 10,000 miles annually and can save them 20 to 40% compared to traditional policies. Nationwide SmartMiles leads the pack on availability and flexibility. Allstate Milewise rewards cars that spend more time parked than moving. Mile Auto protects your privacy. And USAA SafePilot Miles offers some of the strongest value for military families in the country.
The real question isn't which program is best in the abstract. The real question is: how many miles did you actually drive last year?
If that number is lower than you expected — and for millions of Americans, it is — then you're almost certainly overpaying right now. And that's a problem with a very straightforward solution.
Get the quotes. Do the math. And stop paying for miles you'll never drive.
Comments
Post a Comment
Silahkan anda berkomentar dengan baik, jangan melakukan Spam, jangan menyisipkan link aktif,
terima kasih.